Retirement planning for blended families means protecting a spouse and children from prior marriages. Learn wills, trusts, QTIP
Last Updated: November 21, 2026
Quick Summary
Retirement planning for blended families works best when spouses first share and document their goals, then align wills, beneficiary designations and any QTIP trust with those goals. Each plan should protect a surviving spouse’s income while preserving the inheritance intended for children from prior relationships.
Retirement planning for blended families is harder than a standard plan. Two households, shared finances and children from prior relationships all pull in different directions. A plan built for a traditional family often leaves a surviving spouse short or a child unprotected. (Source: Internal Revenue Service guidelines on beneficiary designations)
Most standard plans assume one set of heirs and one spouse. Blended families rarely fit that picture. Here is what usually changes:
A single shared plan can leave someone out. Addressing this usually requires a different starting point.
Open conversation is the first step, and it is the one most families skip. A personalized planning approach can turn those shared goals into a concrete strategy.
A simple way to begin:
Spouses often assume they agree. Putting goals on paper shows where they actually differ.
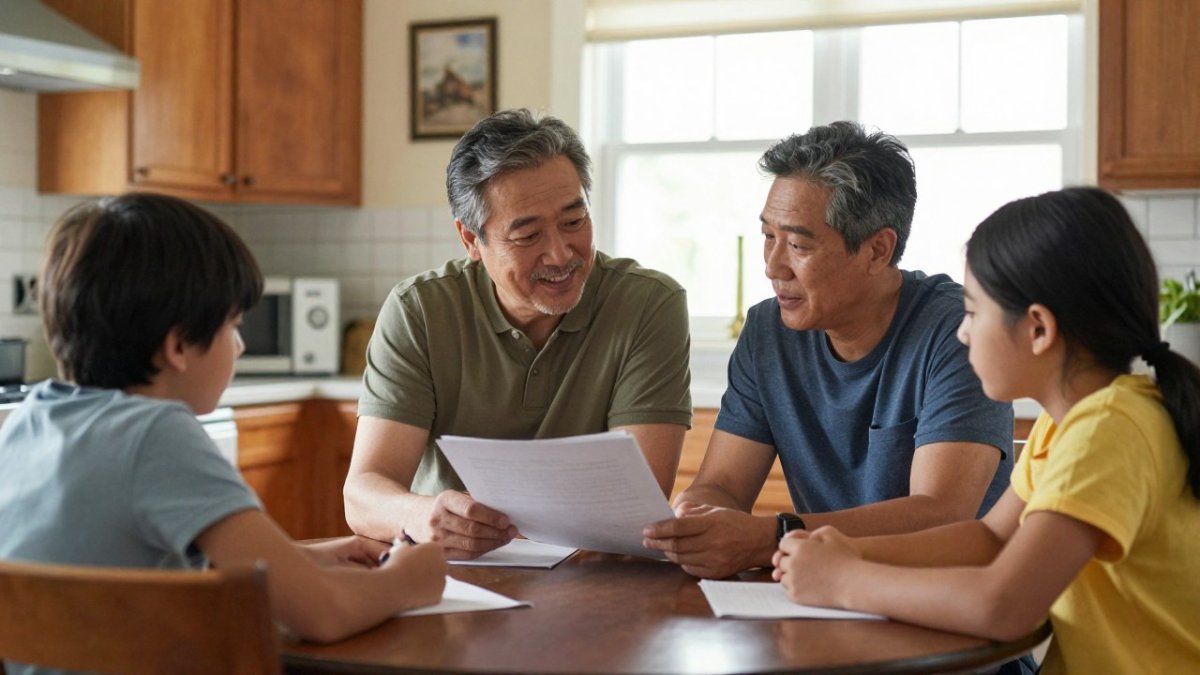
!A middle-aged couple and their adult children seated around a kitchen table, reviewing papers together in a relaxed conversation
A will and beneficiary designations work differently, and this is where many blended families run into trouble. A beneficiary form on a retirement account or life insurance policy usually overrides what the will says.
Check these items after any remarriage:
Keep one rule in mind. The newest form controls, not the newest will. An old beneficiary designation naming a former spouse can send money away from the family you intended to protect.
Fairness in a blended family does not mean everyone gets the same amount. It means each person’s needs and agreements are addressed clearly.
Fairness here means the plan matches what each spouse and child was promised or needs.
Many families use a written agreement to set expectations. A prenuptial or postnuptial agreement can confirm which assets stay separate and which are shared.
A QTIP trust, short for qualified terminable interest property trust, is one tool some blended families consider. It lets a surviving spouse receive income from the trust for life. The principal then passes to the people the first spouse named, often children from the prior relationship.
This structure helps when you want to:
A QTIP trust has tax rules and requirements that must be met. The details depend on your situation, so review them with a qualified estate attorney before relying on one.
Estate distribution is only part of the picture. Blended families also need to consider how two spouses with separate work histories, separate children and possibly separate accounts can fund a shared retirement. This section covers the coordination work that happens while both spouses are alive, plus the incapacity and care planning that helps keep the household financially stable if one spouse cannot make decisions.
Start by listing every income source each spouse will have in retirement, separately, then combine them into one household view. A common pattern looks like this: (Source: American Bar Association’s guide to estate planning)
Blended families often have more accounts, more custodians and more prior beneficiary designations than traditional families. Treat the household as one retirement-income system even when the accounts stay separate:
Watch out: naming a spouse as the primary beneficiary on every account by default can disinherit children from a prior relationship if the surviving spouse later changes their own beneficiary designations. Decide deliberately, account by account, who should inherit and in what form.
Long-term care is the expense most likely to wreck a blended-family retirement plan, because it can consume the assets one spouse intended for their children. Address it directly:
A coordinated plan usually involves a financial planner, an estate attorney and a tax professional working from the same set of assumptions. Bring them the household income map, the beneficiary list and the family agreement so each advisor is solving the same problem. Review the plan together whenever a spouse retires, a pension election is made, or a health event changes the care outlook.
The table below summarises the key coordination steps for blended-family retirement income and care planning.
| Item | Action | Note |
|---|---|---|
| Social Security | Confirm each spouse’s own and survivor benefit | Rules are age-dependent and fact-specific |
| Pensions | Review joint-and-survivor election | Reduces current check, protects survivor |
| Traditional 401(k)s and IRAs | Confirm current RMD timing | Check with tax professional or IRS |
| Withdrawal order | Choose each year based on tax brackets | Avoid default choice of easiest account |
| Survivor stress test | Run plan as if one spouse dies in year five | Adjust through elections, insurance or reserve |
| Beneficiary designations | Name beneficiaries account by account | Prevents disinheriting children from prior marriage |
| Long-term care | Estimate costs and decide funding | Can drain assets meant for children |
| Plan review | Review annually and after family events | Trigger reviews within 30 to 90 days |
A blended-family plan is not finished when the documents are signed. It is a living system that has to be re-checked whenever the family changes. The families who avoid unintended disinheritance are usually the ones who built a review habit, not the ones who bought the most elaborate trust.
Put two kinds of reviews on the calendar:
A relocation matters more than most people expect. State law governs wills, trusts, powers of attorney, health directives and property rules, so a move can change how your documents are interpreted. Have an attorney in the new state review the plan after a move.
Use this order at each review so nothing gets skipped:
Watch out: beneficiary forms and wills are often updated at different times by different people. If the two disagree, the beneficiary form usually wins for retirement accounts and life insurance, so update the forms in the same sitting as the will, not months later.
A few habits keep the plan from drifting:
If your family has changed recently, this is the right time to act. Lineage Guardians offers personalized retirement planning for blended families, and you can book a planning consultation to review your current plan.
Start by listing each spouse’s retirement income sources, including Social Security, 401(k) or 403(b) accounts, pensions and savings, and identify which assets are shared and which are separate. Agree on goals for the current spouse and for children from prior marriages before choosing any strategy. Then work with a financial planner and an estate attorney to coordinate beneficiary designations, retirement income and legal documents so one household’s plan does not unintentionally undercut the other’s. Review the plan at least once a year and after any major life change.
Blended families often use separate wills, or a joint will with clear provisions, to specify who receives what. Beneficiary designations on retirement accounts and life insurance override a will, so they must be updated after a remarriage. Many families also use trusts to control when and how children receive assets. Because state probate and community property rules vary, confirm the details with a licensed estate attorney in your state.
Yes. A trust can provide income to a surviving spouse for life while preserving the remaining assets for children from a prior marriage. A QTIP trust, which qualifies for the marital deduction under federal estate tax rules, is one common option, but its suitability depends on the family’s estate size and goals. Trusts involve setup and ongoing administration costs, so compare options with a qualified estate attorney before deciding.
Review your plan at least once a year and after any major event, such as a marriage, divorce, death, birth of a grandchild, job change or significant shift in assets. Check beneficiary designations, account titles, trust terms and powers of attorney, since outdated documents are a frequent source of family conflict. Keeping a single written summary of your plan helps your spouse, children and advisors stay aligned.
